FHA HECM Reverse Mortgages
Since 1993, we’ve helped thousands of people — just like you — use the right reverse mortgage to build stability, confidence, and freedom in retirement.
Helping You Stay Happy, Secure, and at Home in Retirement
At Carrollton Mortgage, we know you want to be a confident, happy homeowner — today and throughout retirement. To get there, you need financial flexibility that allows you to enjoy life on your terms, without the pressure of monthly mortgage payments.
But here’s the challenge:
As costs rise and life evolves, many retirees face the uncertainty of how to access cash while staying in the home they love.
That’s where an FHA Reverse Mortgage, also known as a Home Equity Conversion Mortgage (HECM), can help.
It’s the only reverse mortgage insured by the U.S. government — and one of the most powerful tools for giving homeowners aged 62 or older the ability to tap into their home’s equity while aging in place.
Flexibility and Key Features of an FHA Reverse Mortgage
✅ Access a portion of your home’s equity based on the age of the youngest borrower or eligible non-borrowing spouse, current interest rates, home value, existing liens, and FHA program limits. For 2026, the nationwide HECM maximum claim amount is $1,249,125.
✅ Stay in your home indefinitely — just keep up with property taxes, insurance, home maintenance, applicable HOA charges, and other loan requirements.
✅ Use a HECM to purchase a new primary residence if it fits your goals.
✅ No required monthly principal-and-interest payments on the HECM — repayment typically happens when the last borrower leaves the home or passes away.
✅ Line of Credit Option: HECM credit lines remain fully available for the life of the loan as long as terms are met and available principal limit is not exhausted — unlike non-HECM reverse lines that often expire after 10 years.
✅ Tenure Payments Option: Receive monthly payments for as long as at least one borrower continues to occupy the home as their principal residence and loan requirements are met — providing reliable cash flow without selling your home.
✅ Only one spouse needs to be 62 or older. A spouse younger than 62 may be treated as an eligible non-borrowing spouse. Certain protections may allow an eligible non-borrowing spouse to remain in the home after the borrowing spouse dies, provided HUD requirements and the terms of the loan continue to be met. The age of the youngest borrower or eligible non-borrowing spouse also affects how much may be available.
✅ Like all reverse mortgages, the loan is secured by your home and accrues interest — which means equity will decrease over time as interest compounds until the loan is repaid.
Who Qualifies for an FHA HECM Reverse Mortgage?
A Home Equity Conversion Mortgage is generally available to homeowners age 62 or older who occupy the property as their principal residence. The home must meet FHA property requirements, and the borrower must have enough equity for the transaction to work.
FHA also requires a financial assessment to determine whether the borrower has the financial capacity and willingness to meet ongoing obligations such as property taxes and homeowners insurance. Before obtaining a HECM, borrowers must complete counseling with a HUD-approved HECM counselor.
Eligible properties can include many one-to-four-unit homes, certain condominiums, townhomes, and qualifying manufactured homes.
Why Work With a Certified Reverse Mortgage Professional?
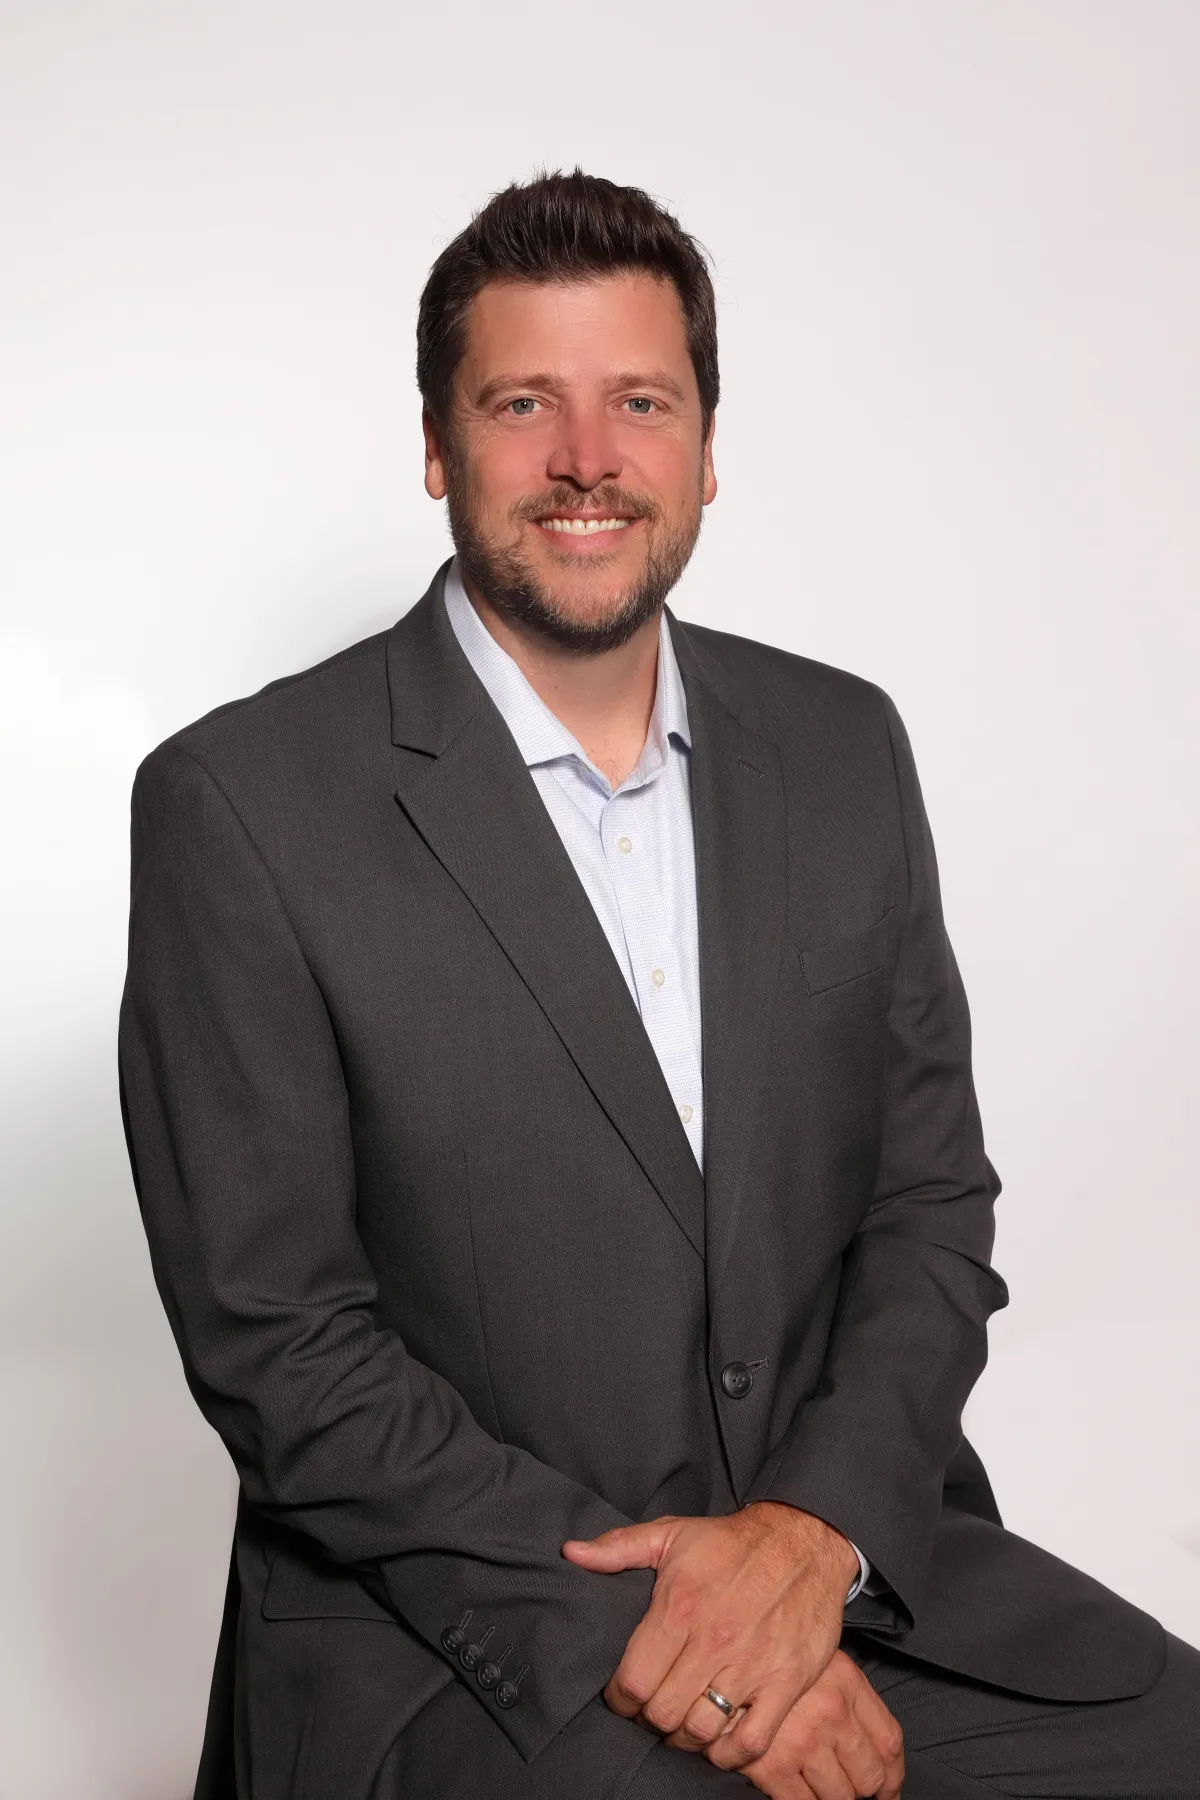
Adam Weinert, President and co-owner of Carrollton Mortgage, is a Certified Reverse Mortgage Professional (CRMP). The CRMP designation is a specialized reverse mortgage credential that requires industry experience, education, examination, adherence to a professional Code of Ethics, and ongoing continuing education.
Reverse mortgages can be powerful financial tools, but they are not right for everyone. Adam helps California homeowners understand their options, compare HECM and private reverse mortgage programs, and make informed decisions based on their individual goals.
HECM Frequently Asked Questions
What is a HECM reverse mortgage?
A Home Equity Conversion Mortgage (HECM) is an FHA-insured reverse mortgage for eligible homeowners age 62 or older. It allows you to access a portion of your home equity while continuing to own and live in your home, as long as loan requirements are met.
How much can I borrow with a HECM?
The amount available depends on factors including the age of the youngest borrower or eligible non-borrowing spouse, current interest rates, home value, existing liens, and FHA program limits. For 2026, the nationwide HECM maximum claim amount is $1,249,125.
Do I still own my home?
Yes. You remain the owner of your home and keep title to the property. The HECM is a loan secured by your home, and you remain responsible for property taxes, homeowners insurance, maintenance, and other applicable property charges.
Can I get a HECM if I already have a mortgage?
Yes, in many cases. An existing mortgage is typically paid off with HECM proceeds at closing. The amount of equity remaining after that payoff helps determine how much additional loan proceeds may be available.
When does a HECM become due?
A HECM generally becomes due when the last borrower sells the home, permanently moves out, or dies. It may also become due if loan requirements are not met, such as keeping property taxes and homeowners insurance current or maintaining the home as a principal residence.
At Carrollton Mortgage, our goal is to help you understand your options clearly so you can make the choice that best supports your long-term financial security and helps you remain a happy homeowner.
For more information on reverse mortgages, click the links below
Buy a home with a reverse mortgage

Flexible payment loans for Seniors
Jumbo reverse mortgages
Private reverse mortgages
Second lien reverse mortgages
How We Help You Become a Happy Homeowner
Start the conversation – Call us at 888.730.5200
We'll work together to find the right loan for your goals
Enjoy life as a happy homeowner with stability and confidence
888.730.5200
NMLS 235659 • DRE 01073847
© Copyright 2026. Carrollton Mortgage All rights reserved.
Carrollton Mortgage Co. is licensed in California. The intent of this website is only to advertise to those interested in financing real estate in California.